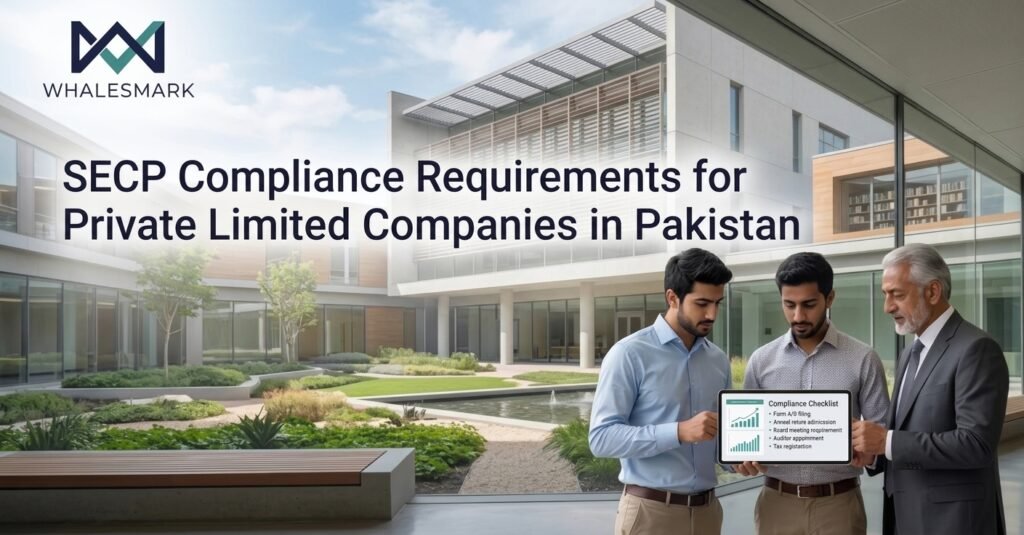
Private limited companies in Pakistan must follow specific legal and regulatory obligations to maintain their registered status and operate within the country’s corporate framework. The Securities and Exchange Commission of Pakistan (SECP) regulates company registration, statutory reporting, corporate records and other compliance matters under the Companies Act, 2017, and the applicable regulations.
Understanding SECP compliance requirements in Pakistan is important for business owners, directors and shareholders because compliance involves more than registering a company. Companies must maintain accurate records, report relevant changes, meet applicable filing deadlines and fulfil their financial reporting responsibilities. A structured approach to Private limited company compliance in Pakistan helps businesses avoid unnecessary regulatory complications and maintain transparent corporate operations.
Table of Contents
Understanding SECP Compliance for Private Limited Companies
The Companies Act, 2017, establishes the legal framework governing private limited companies in Pakistan. SECP oversees the regulatory requirements applicable to incorporated businesses, including corporate information, management changes, financial statements and statutory returns.
The specific obligations depend on factors such as the company’s paid-up capital, ownership structure, activities and applicable legal exemptions. Therefore, SECP compliance requirements in Pakistan should be assessed according to the company’s circumstances rather than treated as a single checklist applicable to every business.
Maintaining updated corporate records, observing filing deadlines and following the company’s memorandum and articles of association are important elements of Corporate compliance for private limited companies.
Annual Returns and Corporate Information
Annual returns are an important part of a company’s reporting responsibilities. Under Section 130 of the Companies Act, 2017, companies are required to submit annual returns in the prescribed format, subject to applicable exemptions.
Companies with share capital generally use Form A, while Form 24 is relevant where there has been no change in the particulars reported in the previous annual return, subject to the applicable rules. Certain single-member companies and private companies with paid-up capital not exceeding Rs. 3 million may qualify for exemptions from filing the annual return where the statutory conditions are satisfied.
SECP annual returns provide information about a company’s directors, chief executive, registered office, shareholders and share capital. Businesses should ensure that the information submitted reflects their actual corporate position.
For companies required to file, the applicable deadline must be observed. SECP guidance generally specifies filing within 30 days of the annual general meeting for other companies, with relevant provisions applying to single-member companies and companies qualifying for exemptions.
Accurate preparation of SECP annual returns supports transparent reporting and helps maintain reliable corporate records.
Financial Statements and Accounting Responsibilities
Private limited companies must maintain proper accounting records and prepare financial statements in accordance with the Companies Act, 2017. However, the requirement to file financial statements with SECP depends on the company’s classification and paid-up capital.
Under SECP guidance, private companies and single-member companies with paid-up capital of up to Rs. 1 million, provided they are not subsidiaries of public companies, are required to file annual unaudited financial statements. Private companies exceeding the applicable threshold generally fall within the requirements for filing audited financial statements.
Where applicable, financial statements must be approved by the board and signed by the authorised individuals. Companies must also observe the relevant requirements for holding annual general meetings and presenting financial statements to shareholders.
These obligations form an important part of Private limited company compliance in Pakistan, as accurate accounting records support financial transparency and responsible management.
Statutory Filings and Reporting Changes
Companies must notify SECP when certain changes occur in their corporate structure or official information. These obligations may arise from the appointment or resignation of directors, changes in officers, share allotments, changes in shareholding and other reportable corporate events.
For example, particulars of directors and officers are reported through the prescribed filing process, generally using Form 9 under the current regulatory framework. The applicable filing deadline for reporting appointments or changes is generally 15 days.
Similarly, a company issuing additional shares must comply with the relevant allotment and reporting requirements. Certain changes in shareholding, registered office information, charges and constitutional documents may also trigger specific filings.
These Company statutory filings in Pakistan are essential because they keep the regulator’s records consistent with the company’s actual structure and activities. Timely reporting is therefore a key element of Corporate compliance for private limited companies.
Ultimate Beneficial Ownership Requirements
Companies must also pay attention to ultimate beneficial ownership (UBO) disclosure obligations under Section 123A of the Companies Act, 2017.
The purpose of these requirements is to identify the natural persons who ultimately own or control a company. Businesses must maintain the prescribed beneficial ownership information and obtain relevant declarations from members.
SECP’s Companies Regulations, 2024, provide procedures for the applicable declarations and reporting, including Form 19. Companies must follow the prescribed requirements and timelines for submitting the relevant information.
UBO reporting is another important consideration when reviewing SECP compliance requirements in Pakistan, particularly for businesses with multiple shareholders or layered ownership arrangements.
Managing Compliance and Avoiding Regulatory Delays
An organised compliance process can help companies manage their regulatory responsibilities more effectively. Businesses should maintain updated registers, record board and shareholder decisions, monitor changes in ownership and management, and keep accounting information properly documented.
They should also review upcoming filing deadlines and use SECP’s eZfile system for applicable electronic submissions. Companies should check their filing status and respond promptly if SECP requests clarification or additional information.
A consistent approach to Company statutory filings in Pakistan, together with properly maintained financial and corporate records, can reduce the risk of missed deadlines and administrative complications.
How Whalesmark Supports Corporate Compliance
Whalesmark recognises the importance of structured business management, sound governance and informed corporate decision-making. Businesses need reliable processes to manage their responsibilities as they develop and expand.
Understanding Private limited company compliance in Pakistan allows business owners to make better-informed decisions about corporate administration and regulatory obligations. By keeping SECP annual returns, financial records and other reporting responsibilities organised, companies can strengthen their internal management practices.
Corporate compliance for private limited companies should be treated as an ongoing business responsibility rather than a task completed only during registration. With appropriate planning and professional guidance, businesses can approach their regulatory obligations with greater clarity and confidence.
Conclusion
Meeting SECP obligations is an essential responsibility for private limited companies operating in Pakistan. From annual returns and financial statements to beneficial ownership declarations and event-based reporting, each requirement serves a specific regulatory purpose.
A clear understanding of SECP compliance requirements in Pakistan helps companies maintain accurate records, fulfil applicable legal obligations and establish a stronger foundation for sustainable business operations. Businesses should regularly review current SECP requirements and seek qualified professional advice where their circumstances require it.
Frequently Asked Questions
1. What are the SECP compliance requirements for private limited companies in Pakistan?
They include annual returns where applicable, financial reporting, audit obligations, reporting changes in directors, beneficial ownership disclosures and maintaining statutory records.
2. When must a private limited company file its annual return with SECP?
Generally, companies must file their annual return within 30 days of their annual general meeting, subject to applicable exemptions under the Companies Act, 2017.
3. Is an annual audit mandatory for every private limited company in Pakistan?
No. Private companies with paid-up capital not exceeding Rs. 1 million, which aren’t subsidiaries of public companies, are generally exempt from statutory audit requirements.
4. What is the penalty for non-compliance with SECP regulations?
Penalties depend on the specific regulatory violation. Failure to submit required returns, maintain statutory records or meet reporting obligations can result in fines and other regulatory action.